News
Bard Santner wants to turn Zimbabwe's diaspora remittances into a banking business
Bard Santner’s latest gambit is less about chasing a quick fee‑cutting win and more about turning the $2.45 billion Zimbabwean diaspora flow into a steady stream of deposits and loans.
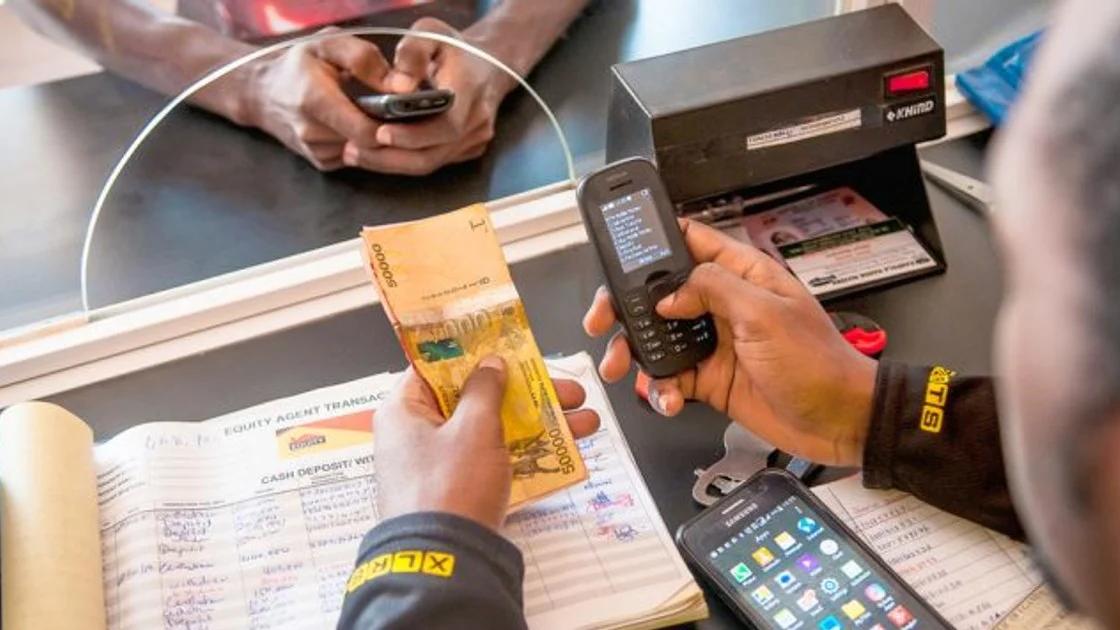
Bard Santner’s latest gambit is less about chasing a quick fee‑cutting win and more about turning the $2.45 billion Zimbabwean diaspora flow into a steady stream of deposits and loans. For the millions of Zimbabweans abroad who send money home each month, this means a bank that can keep their money in the country instead of funneling it through a thin‑margin remittance service. For the firm, it is a strategic pivot from a transactional play to a full‑spectrum banking model that promises higher customer lifetime value. The stakes are high: if the move fails, the remittance corridor could stay a one‑way street; if it succeeds, it could rewrite how diaspora money circulates in Southern Africa.
Remittance operators have long been squeezed by price wars. Every cent saved on a transfer is a win for the customer, but it also erodes the provider’s margins. Bard Santner is betting that once a user trusts the platform enough to send money home, the same relationship can be leveraged for savings accounts, micro‑loans, and wealth‑management products. The firm’s new deposit‑taking micro‑finance bank is the vehicle for this shift. By bundling credit and savings onto existing cross‑border flows, Bard Santner aims to convert one‑off remittance users into long‑term banking clients. The logic is simple: a customer who regularly sends money home has a predictable cash‑flow pattern, making them a low‑risk borrower and a valuable savings holder. The challenge lies in building the infrastructure to support seamless cross‑border clearing and ensuring that the bank can offer interest rates and credit terms that outshine both traditional banks and pure‑play remittance firms.
South Africa’s banking scene has been transformed by digital challengers. A PwC analysis showed digitally active clients rose to 27.6 million in the second half of 2025, up from 21 million in the first half. This surge has turned cross‑border payments into an entry point for broader financial services. Digital banks such as GoTyme, Bank Zero, and Discovery Bank now compete aggressively on transaction costs and yields, while remittance incumbents like Mukuru, Mama Money, and Hello Paisa maintain deep distribution networks across primary migrant corridors. Bard Santner’s strategy hinges on bridging these two models. The real battleground is customer retention across borders: will the diaspora choose a bank that offers more than just cheap transfers, or will they stick with the familiar, low‑fee remittance channels?
For a remittance‑first bank, capital efficiency is the lever that can turn transactional volume into profitability. A customer who sends money regularly represents lower acquisition costs for credit and savings products, provided the bank can deliver a frictionless cross‑border experience. Traditional banks still face a friction‑heavy gap in cross‑border integration, while remittance providers are forced to expand into deposit‑taking to defend against margin compression. Bard Santner’s success will depend on offering clear interest differentials or direct credit access tied to historical transfer data. If the firm can deliver on this promise, it could set a new standard for diaspora banking in the region.
Formal diaspora remittances reached $1.62 billion in the first seven months of 2026, up 24 % year‑on‑year, according to Reserve Bank of Zimbabwe data. Yet these gross inflows mask a structural problem: the money is moving through thin‑margin channels that do not generate lasting financial relationships. Bard Santner’s move to a deposit‑taking model is an attempt to capture a larger share of that value. If successful, the firm could not only grow its own customer base but also help stabilize the Zimbabwean economy by keeping more capital within the country’s banking system.
I predict that within the next two years Bard Santner will secure a 5 % market share of the Zimbabwean diaspora remittance corridor, translating into roughly $120 million in annual deposits. This shift will force incumbents to rethink their fee structures and expand their service offerings. If the bank can deliver on its promise of higher yields and seamless cross‑border integration, it will set a new benchmark for how diaspora money can be turned into a sustainable banking ecosystem.
Bard Santner’s gamble is a bold step toward turning a one‑way money flow into a two‑way financial partnership. Whether it succeeds will depend on its ability to blend the low‑cost, high‑volume nature of remittances with the depth and stability of traditional banking services. The next few years will reveal whether this hybrid model can truly change the game for Zimbabwe’s diaspora.